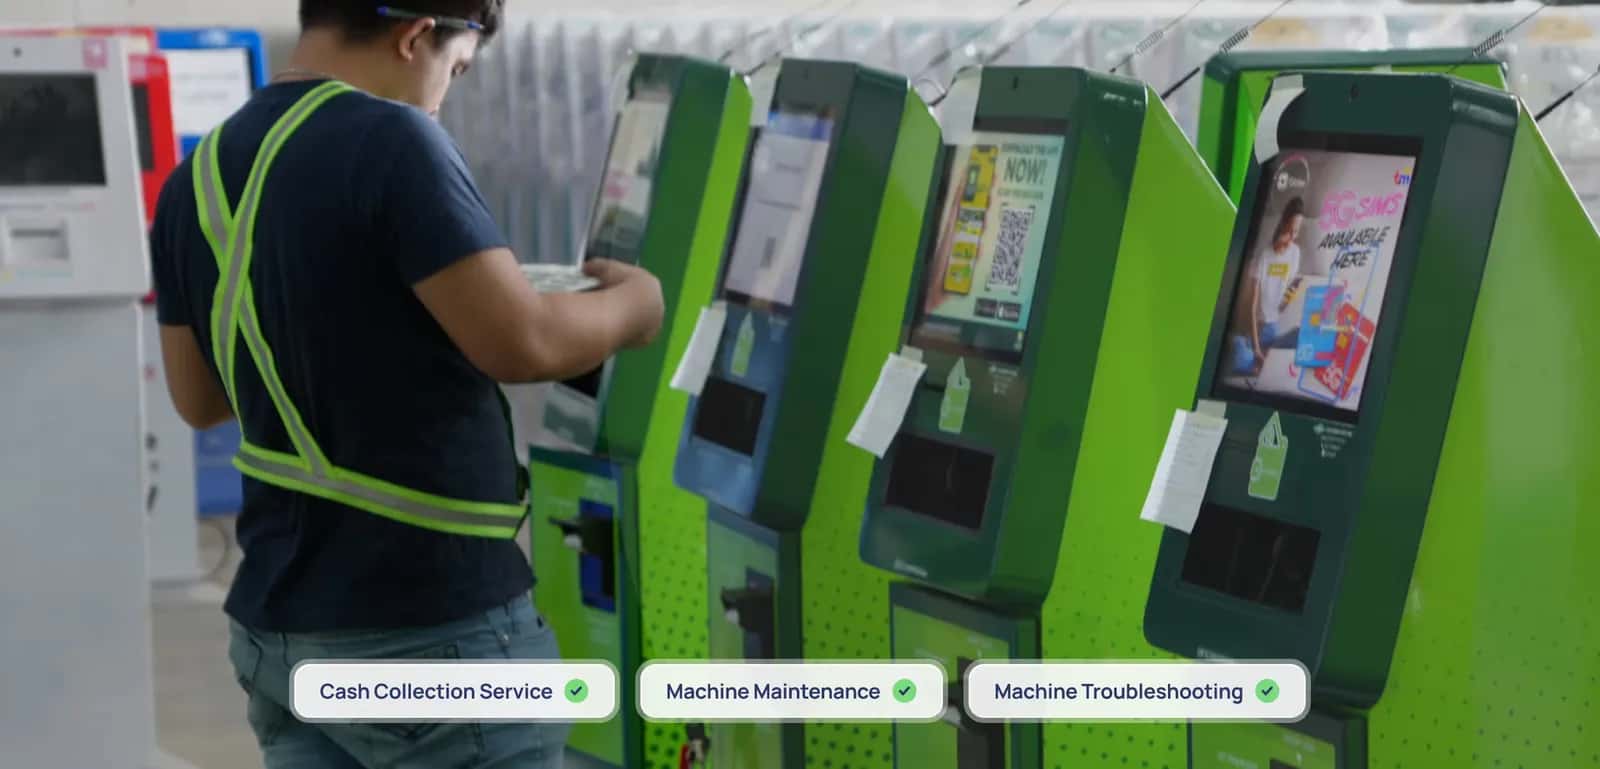
Palawan Express Pera Padala
Payment & Remittance Center
- Franchise fee
- No franchise fee
- Total investment
- ₱100k–₱500k
🎁 Start Your 1 Month Free Trial of the Full Plan, Exclusively for Brands & Advisors.Get Started
Browse 2 financial services franchises up to ₱500k, with investments of about ₱500k each, a franchise fee of about ₱50k, and most paying back in 12 to 18 months.
Updated
Payment & Remittance Center
Payment & Remittance Center
Up to ₱500,000, financial services franchising covers an unusually wide entry range, from about ₱100,000 to the full ₱500,000. Fees stay modest, from nothing at all up to ₱50,000. Payback moves between a year and a year and a half. Which end of that timeline a buyer lands on depends more on the specific name chosen than on the total amount actually spent up front. The real decision at this budget is how much physical space to build, not which name looks strongest on paper.
Entry into this budget spans from about ₱100,000 at the low end to the full ₱500,000, a fivefold difference that is unusually wide for one price range. Franchise fees stay modest on both ends, from nothing at all up to ₱50,000. Most of the real gap between the cheaper and pricier option comes from the scale of the physical build itself, not from what any name charges for the underlying brand. The time it takes to earn that money back stays fairly steady, landing somewhere between twelve and eighteen months either way. The pricier option is not simply a slower-paying version of the cheaper one. A buyer holding only ₱100,000 in hand can still realistically reach more than just the very cheapest name available at this budget. Reading the ₱500,000 figure as the entry price, rather than the only price, keeps the search from narrowing too early.
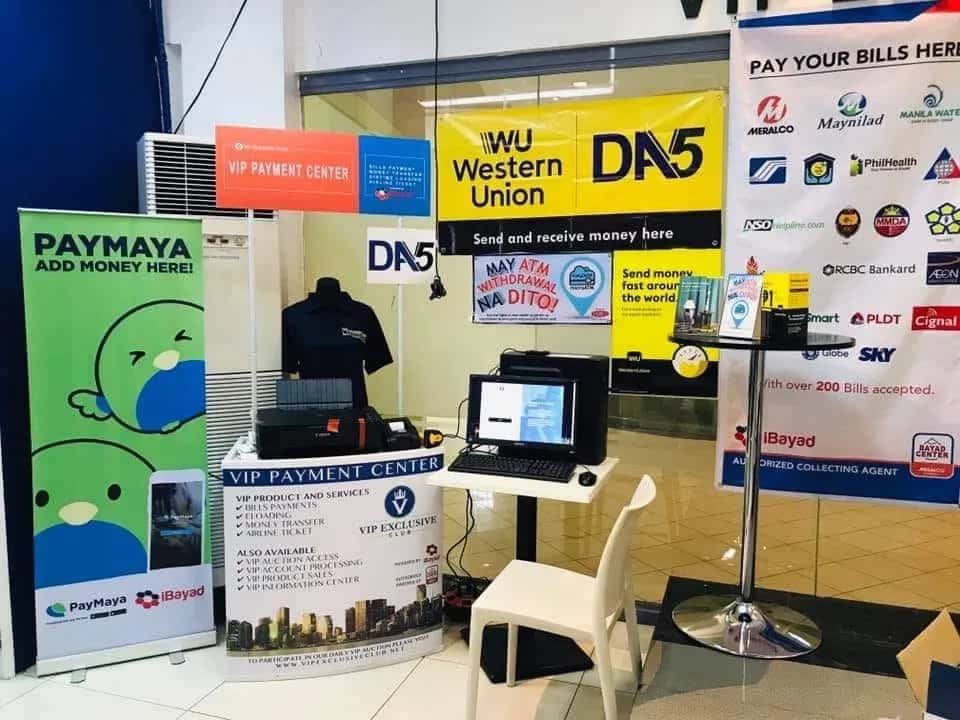
Every name at this level narrows down to a physical shape choice. A buyer can choose a proper shop with its own dedicated floor space, or a smaller counter built for a faster transaction. The fivefold gap in total investment described above comes down almost entirely to which shape, and at what scale, a buyer chooses to build. A buyer with ₱100,000 to spend is not locked out of any name, but is likely limited to the leaner counter version. A buyer with the full ₱500,000 can build out a fuller shop instead. That flexibility means the real decision at this budget is less about picking between names and more about deciding how much physical space to fund. A quiet residential corner rarely calls for the same level of investment as a busy commercial strip with heavy daily foot traffic. Matching the build to the actual foot traffic of the spot in mind, rather than to the top of the budget, tends to produce a better return either way.
Because the fee stays low across this range, most of what a buyer pays goes into equipment, signage, and the physical build rather than into training or brand support. The owner should expect to be closely involved in day-to-day operations regardless of which end of the investment range they choose. Handling customer remittances or payments directly means cash reconciliation and security become part of the daily routine from the very first day. That responsibility does not scale down just because a buyer picked the leaner ₱100,000 setup. Treating the first year as a period of steady, hands-on management, not a passive investment, is the more realistic approach at either end of this budget. Handing the counter to hired help too soon, before the process is second nature, tends to invite the kind of small mistakes that erode a customer's trust fast. Building that muscle memory personally in the first few months tends to pay off well beyond the first year.
Deciding where to land within this fivefold range should start with the space realistically available, not with the name on the sign. Someone with only ₱100,000 to work with should plan around a lean counter operation from the outset rather than stretch toward a half-built shop that never gets finished. Someone approaching the full ₱500,000 should confirm what a fuller build actually adds in terms of customer trust and transaction volume before assuming bigger automatically means better. Asking for examples of both a lean and a fuller existing location helps ground that decision in something more concrete than the published range alone. Talking to an existing owner of each, where one can be found, tends to surface more of that difference than any brochure ever will. Deciding the build size before falling for a specific name keeps the whole search grounded in what the space can actually support.
Now that you've seen what's here, a real advisor can help you shortlist and weigh the options against your budget. Free, at your pace.
Financing Readiness · Site Selection
Low-Capital Startups
Franchise Agreements · Multi-Unit Expansion
Low-Capital Startups · Site Selection
Are you a franchise advisor?Get your own workspace here
Choose a kind of financial services business and see only its franchises up to ₱500k, with their fees and investment ranges.
Get honest answers on fees, payback and the best setups for your area, free and with no pressure.
Keeping things realistic, ₱500k covers two financial services franchises with an investment between ₱400k and ₱500k. Where a package sits inside that range matters, because one near the top leaves less money for everything else. Compare the lower and upper ends and see what extra the higher packages actually add. If the added items are ones you can live without, the cheaper options give you the same start. Use that comparison to trim the list to a few that fit your budget with room left.
Registering your business early can make raising ₱500k for a financial services franchise easier, especially with formal lenders. A DTI or SEC registration, barangay clearance and BIR registration show that you are serious and that the venture exists on paper. Start the registration process while you are still saving so the documents are ready when a bank or cooperative asks for them. Having these papers early also gives you time to fix any errors without delaying a loan.
Inclusions in a ₱500k offer may be described in loose terms like complete equipment set or full training, and those phrases can hide a lot. Equipment, stock, training and signage are common, but you need specifics. Ask for model names or descriptions of each piece of equipment and the number of training days, so the inclusions list becomes something you can actually check against delivery.
Most estimates put payback for a financial services franchise at the ₱500k level at around 12 to 18 months, based on what franchisors themselves report. That figure can stretch once you add costs a sales pitch tends to skip, such as rent, wages and electricity. A useful exercise is to list every monthly expense you expect, subtract it from realistic monthly sales, and divide your total startup cost by what remains. The result is a payback figure of your own that you can set beside the franchisor's.
Possibly, but only after you add the costs a headline quote never shows. The two financial services franchises quoting an investment between ₱400k and ₱500k each leave out the rent deposit, permits, renovation, opening stock and working capital in some combination. Request a written list of what the quote covers, then price every missing item yourself and add it on top. Whether ₱500k is enough depends on that adjusted total, not on the headline figure alone.
Local community marketing is a cost you control, but it still needs room in your budget beyond ₱500k. Sponsoring a barangay event, giving discounts to nearby offices or schools, or printing flyers for your neighborhood can bring in your earliest regular customers. Pick a few low cost ideas, give each a small budget, and keep the ones that clearly bring people through your door.
When your savings are limited, a financial services franchise at ₱500k can feel like the safest door into business, though limited savings call for extra caution. Cut your spending for a few months before you commit and watch how you manage. If you can live comfortably on less, you gain both a bigger cushion and proof of discipline. If it feels painful, the budget may be too tight for now.
Prices between ₱400k and ₱500k separate kiosks with 2 franchises and inline stores with 2 for a financial services franchise at ₱500k, but the daily difference is usually size and crew. A larger unit holds more customers and needs more people, while a smaller one serves fewer at a time with a lighter team. Look at how many customers pass your spot in an hour and how many each format can serve, and choose the unit whose capacity is close to that flow.
Compare how many financial services franchises start at each budget level, from the smallest packages up.
Financial Services franchises priced close to your budget, worth a look if you can stretch your savings or want to spend less.
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center

Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Compare financial services franchises with other industries at the same budget, each with its own brands, fees and investment ranges.
Carts, kiosks, and full restaurants.
31 brandsFrom ₱50k
Chops To Go, Samurai Foods, Kettle Korn +28 more
See brands
4 brandsFrom ₱150k
Truewin, Keno Lotto Express Outlet, Picturebooks +1 more
See brands
Bread, cakes, and pastry shops.
3 brandsFrom ₱200k
Don Benito's Cassava Cake, Magic Melt, Mrs. Pandesalan
See brands
Coffee, milk tea, and cold drink shops.
3 brandsFrom ₱150k
Barista Choi, Happy Kopi, Tea Generation
See brandsCompare industries by budget, daily work and payback before you choose one, free and with no pressure.
Learn practical inventory control steps for your Philippine franchise to cut waste, prevent loss, and protect your capital.
Aug 14, 2026 6 min read
Learn how non-compete clauses work when exiting a franchise agreement in the Philippines, protecting your investment after closing.
Jul 20, 2026 5 min read
Learn how to secure financing for your Philippine franchise, from preparation to approval. A practical guide for new operators and OFWs.
Jul 20, 2026 5 min read