TouchPay
Payment & Remittance Center
- Franchise fee
- ₱350k
- Total investment
- ₱350k–₱400k
🎁 Start Your 1 Month Free Trial of the Full Plan, Exclusively for Brands & Advisors.Get Started
Browse 3 financial services franchises up to ₱400k, with investments from ₱350k to ₱400k, franchise fees mostly between ₱252k and ₱350k, and most paying back in 6 to 24 months.
Updated
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Up to ₱400,000, financial services franchising splits sharply on price. Fees run anywhere from free to ₱350,000, almost the entire budget in some cases. Total investment stays fairly tight, from about ₱250,000 to the full ₱400,000. Payback ranges from six months to two years depending on which end of that fee gap a buyer lands on. That single fact, the fee and the wait moving together, is worth holding onto while weighing the rest of this budget.
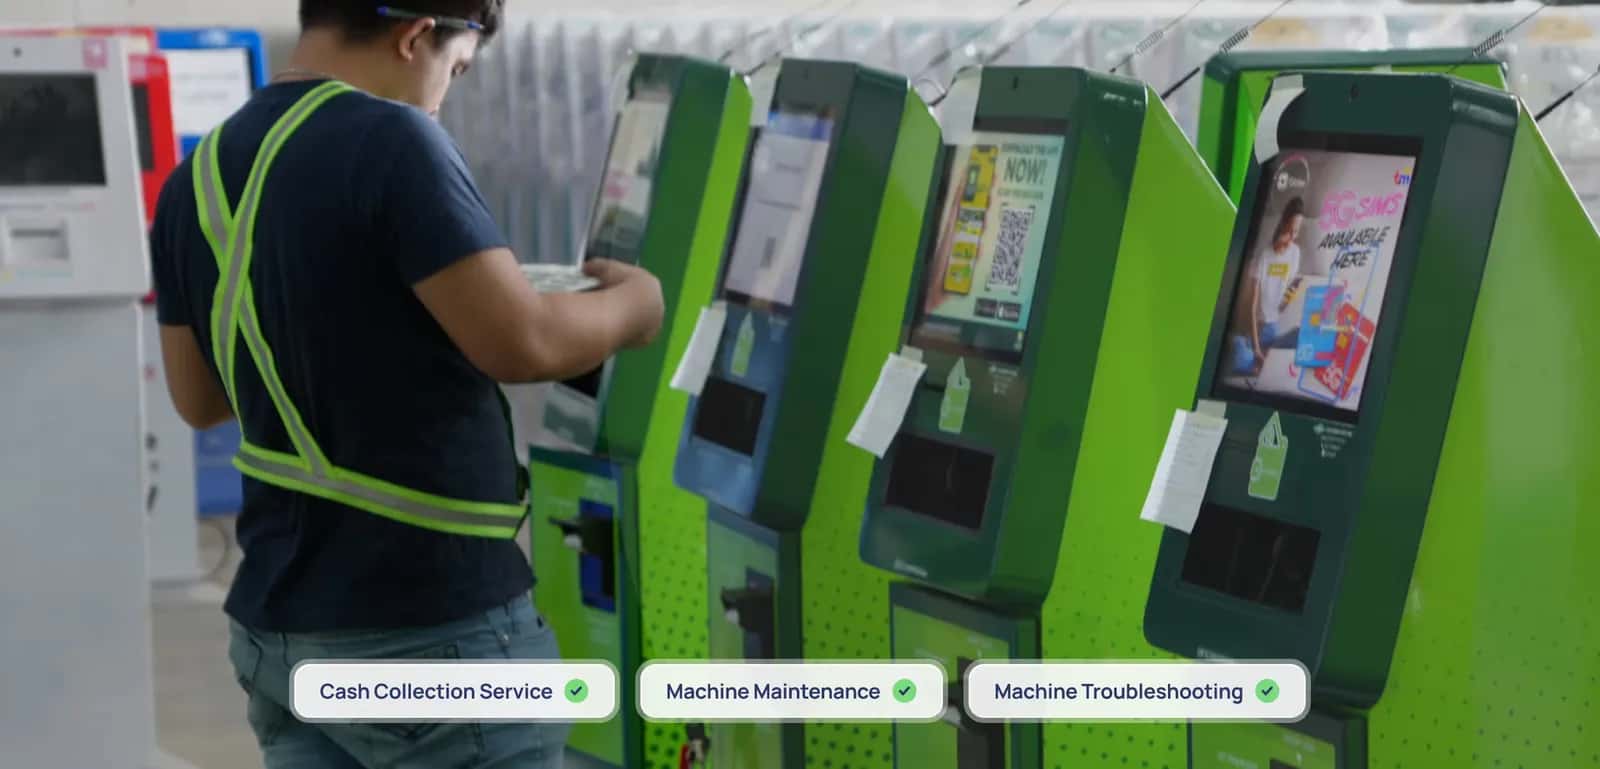
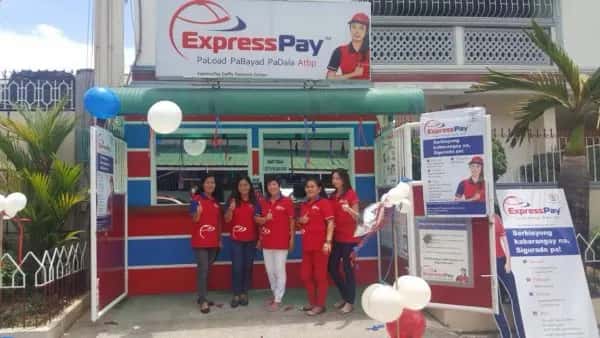
A counter setup comes standard at this budget, available under every name here regardless of price. One in three also offers a full shop with its own walk-in space, and a separate one in three offers a home-based or online arrangement instead. Across the names at this level, a buyer can find a counter, a fuller storefront, or a remote setup without leaving this budget. That spread of formats inside such a tight investment range is unusual for this category, where format tends to narrow sharply once the fee starts climbing toward the top of this budget. A buyer should confirm which specific format a given name actually sells before assuming the category default applies. Names sitting at this exact price can end up feeling like completely different businesses once the format question gets settled. Deciding on the format first, before comparing fees, tends to narrow the search faster than starting from the money alone.
Total investment across this budget sits in a fairly tight range, from about ₱250,000 to the full ₱400,000. The franchise fee tells a very different story, running from nothing at all to as much as ₱350,000, an amount that alone would nearly exhaust the entire budget. Payback follows that same split. The low-fee end can return the investment in as fast as six months, while the highest fee asks for as long as two full years. The fee an owner pays upfront and the time it takes to earn that money back move together here. That runs counter to what a first-time buyer might expect walking in, since a bigger upfront cost usually implies a faster, more polished operation, not a slower one. Reading the fee as a straightforward proxy for quality tends to mislead more than it helps at this particular budget.
This budget suits a buyer willing to do the extra work of comparing a near-free entry against a fee that consumes most of the budget. The two ends demand very different reasoning about brand strength, support, and expected payback. It suits someone flexible on format, since a counter, a storefront, and a home-based setup are all available somewhere in this range. Someone set on one specific physical shape from the outset will find less room to be picky. It does not suit a buyer looking for a straightforward, single-price decision. The spread between the cheapest and priciest option at this exact budget is wider here than at almost any other budget in the category. A buyer arriving with a fixed idea of what this budget should cost may need to adjust that expectation before shopping seriously. Coming in with a range in mind, rather than a single number, tends to make that adjustment far less frustrating.
A buyer weighing the no-fee option against the one asking for nearly the full budget should recognize these as fundamentally different bets rather than a simple discount. The free entry likely trades a much lower upfront cost for less established brand recognition or noticeably thinner training. The top fee, by contrast, buys into whatever track record and existing support network justifies a payback stretching out to two full years. Neither approach is automatically the wiser one. The right answer depends on how much the buyer values a known name and built-in support versus building things themselves for a much lower initial outlay. How comfortable a buyer is carrying that uncertainty through the first full year of operation matters just as much as the number printed on the fee sheet. Talking to someone already running each version, rather than reading the pitch alone, tends to surface that answer faster than any brochure comparison could.
Now that you've seen what's here, a real advisor can help you shortlist and weigh the options against your budget. Free, at your pace.
Financing Readiness · Site Selection
Franchise Agreements · Multi-Unit Expansion
Low-Capital Startups · Site Selection
Low-Capital Startups
Are you a franchise advisor?Get your own workspace here
Choose a kind of financial services business and see only its franchises up to ₱400k, with their fees and investment ranges.
Get honest answers on fees, payback and the best setups for your area, free and with no pressure.
Your pool at ₱400k holds three financial services franchises priced between ₱300k and ₱400k. Counting them is easy, but choosing is not, so give the count a purpose. Use it to decide how much time each option deserves. With this many, make a short first pass over every listing and extend your time only on the ones that survive. That discipline stops one attractive listing from swallowing the effort you owe the others.
If you go by franchisor projections, a financial services franchise in the ₱400k bracket should pay for itself in about 6 to 24 months. Those projections are usually drawn from outlets that are already doing well, so they can look rosier than your opening year will. When you meet the franchisor, ask how the slowest outlets in the network performed, since that tells you more about your downside than the average does.
Separating pre-opening costs from those that can wait lets you fund ₱400k for a financial services franchise in smaller, well-timed amounts. Equipment, training, signage and first stock come bundled in some packages and are charged on their own in others. Read the inclusions item by item, flag anything that savings or early sales could cover after launch, and borrow only for what is due before the doors open. That division keeps any loan modest and far lighter to repay.
Once the ₱400k package is paid, your next big expense is usually the working capital that keeps the doors open. Working capital covers stock, wages, rent and bills during the months when income is still uneven. Talk with existing franchisees about how much cash they needed on hand during their early months, and plan to have at least that available before your opening date.
Working with ₱400k in financial services, you are looking at kiosks with 3 franchises, inline stores with 1 and home-based or online setups with 1. Each format asks for a certain amount of floor area and counter room, so your space decides which ones are possible. Compare the footprint listed for each setup with the measurements of your spot, including the entrance and the area behind the counter, and ask the franchisor whether a slightly smaller or larger layout is accepted.
Moving the outlet later can raise a fee question, even for financial services franchises at ₱400k where the original franchise fee was already paid. Ask whether the contract charges a relocation fee or treats a move as a fresh approval with a new payment. Written terms on this show how flexible your fee really is if your landlord ends the lease or the mall changes. Read that clause before you sign, since the fee you pay now may not cover a later move.
A franchise that fits your schedule is a better first choice than one that fits only your budget, so check whether a ₱400k financial services franchise allows owner absence. Some franchisors require the owner to be present during operating hours, while others accept a trained manager. Ask about this rule directly, especially if you plan to keep your job. Signing a contract you cannot honor is a costly mistake for anyone.
Expect ₱400k to cover what the franchisor treats as the minimum needed to open, often equipment, starter supplies and training. That minimum may be thinner than what your own plans need. Ask for the inclusion list with quantities, such as how many units of each machine, and note any gap between that list and your plan, so you can raise it with each franchisor and compare their replies.
A second opinion can help you judge whether ₱400k is enough before you sign with anyone. The DTI offers free business counseling through its local centers, and an adviser there can look over the costs of the three financial services franchises quoting an investment between ₱300k and ₱400k with fresh eyes. Bring your quotations and your own estimates for rent and running costs, and ask where the plan looks thin, since an outside view often catches gaps you have stopped noticing.
Compare how many financial services franchises start at each budget level, from the smallest packages up.
Financial Services franchises priced close to your budget, worth a look if you can stretch your savings or want to spend less.

Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
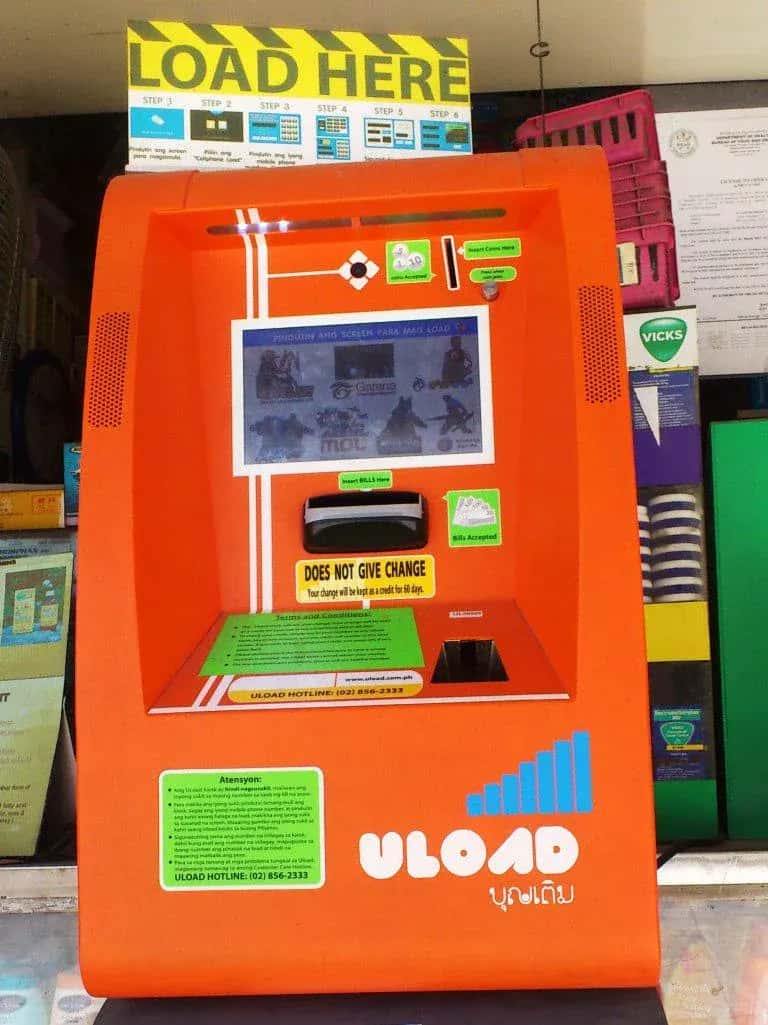
Payment & Remittance Center
Payment & Remittance Center
Compare financial services franchises with other industries at the same budget, each with its own brands, fees and investment ranges.
Carts, kiosks, and full restaurants.
60 brandsFrom ₱29k
Amigo Mango, Buko Express, Burger Factory +57 more
See brands
Coffee, milk tea, and cold drink shops.
10 brandsFrom ₱150k
FaB Caffe', ThirsTEA, Zip 'N Sip +7 more
See brands
Bread, cakes, and pastry shops.
7 brandsFrom ₱250k
Waffle Time, JB's Garlic Pandesal, Lil Orbits +4 more
See brandsCompare industries by budget, daily work and payback before you choose one, free and with no pressure.
Learn practical inventory control steps for your Philippine franchise to cut waste, prevent loss, and protect your capital.
Aug 14, 2026 6 min read
Learn how non-compete clauses work when exiting a franchise agreement in the Philippines, protecting your investment after closing.
Jul 20, 2026 5 min read
Learn how to secure financing for your Philippine franchise, from preparation to approval. A practical guide for new operators and OFWs.
Jul 20, 2026 5 min read