Paylite Corner
Payment & Remittance Center
- Franchise fee
- ₱150k
- Total investment
- ₱350k–₱600k
🎁 Start Your 1 Month Free Trial of the Full Plan, Exclusively for Brands & Advisors.Get Started
Browse 2 payment & remittance franchises up to ₱600k, with investments of about ₱600k each, a franchise fee of about ₱150k, and most paying back in about 18 months.
Updated
Payment & Remittance Center
Payment & Remittance Center
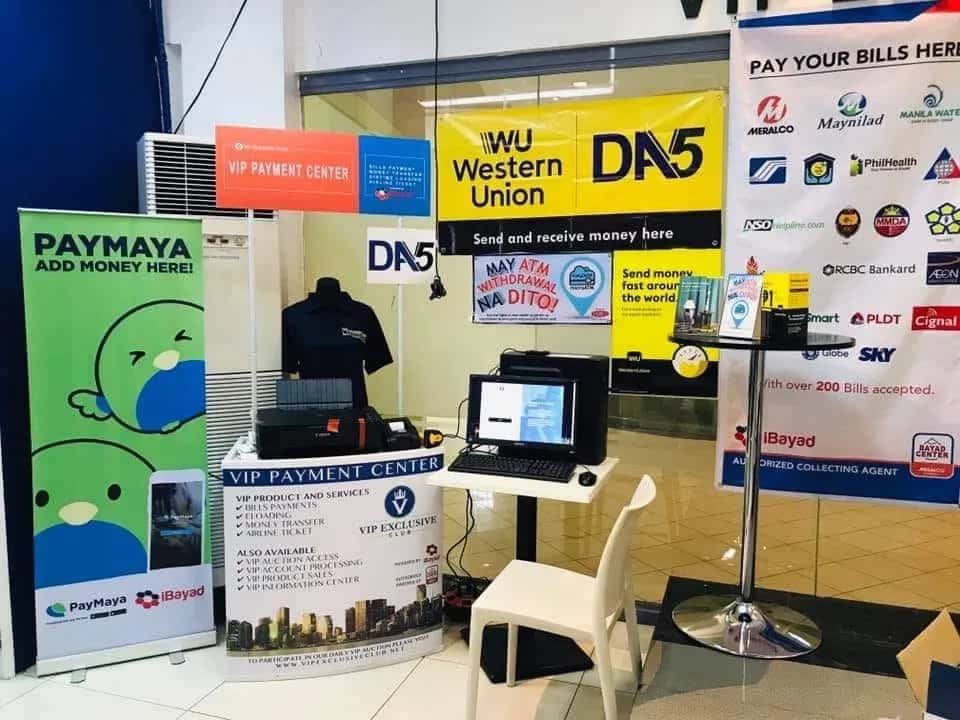
Up to ₱600,000 is a substantial commitment inside payment and remittance, closer to a small branch than a counter. Entry runs from around ₱300,000 to the full ₱600,000, the franchise fee sits at a flat ₱150,000, and payback lands at roughly eighteen months either way. Unlike the smaller budgets in this category, this one is priced for someone building something meant to last, not just to test the idea.
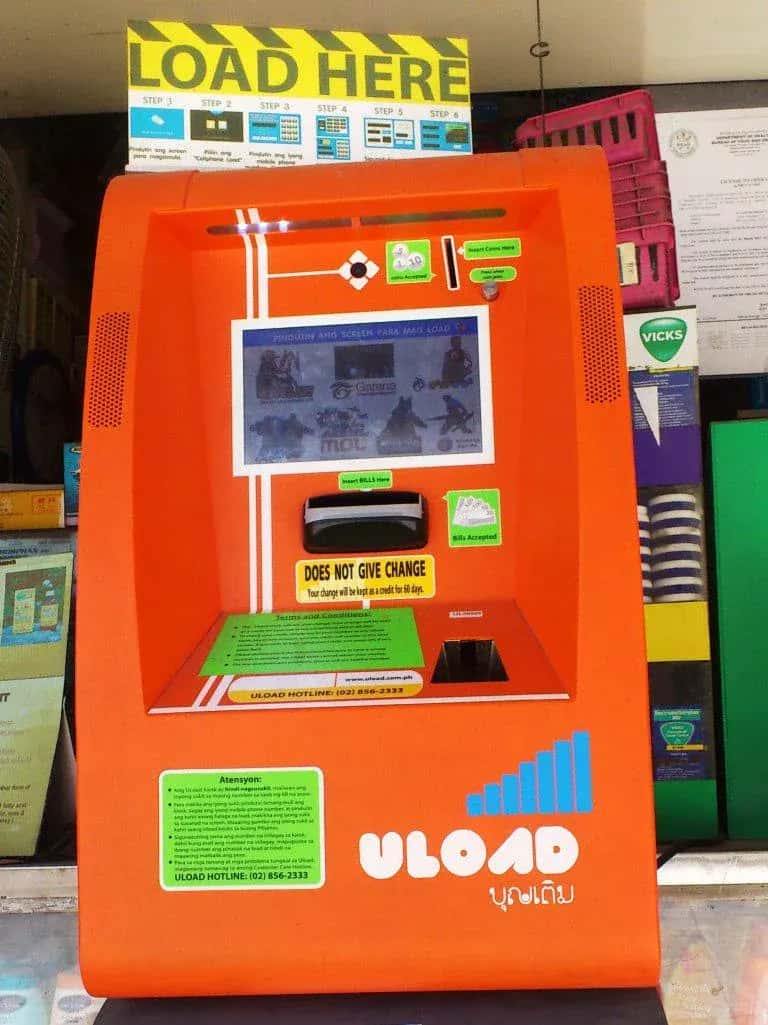
Both the kiosk and the inline store format sit fully inside this budget. Either one can be built out from ₱300,000 to ₱600,000, depending on how much goes into fit-out and equipment beyond the basics. A kiosk at this budget is a stronger version of the same format at a smaller price: better equipment, a more finished counter, and more working capital in reserve. An inline store at this budget means a proper leased space with its own walls. It is capable of handling a fuller service menu and more foot traffic at once than a counter alone could manage. The flat ₱150,000 fee applies regardless of which format is chosen. The real decision is how the remaining ₱150,000 to ₱450,000 gets spent. That decision should follow the site rather than a personal preference for one format over the other, since a kiosk built where a full store was needed, or the reverse, wastes part of this budget before the doors even open. Visiting the intended site at different hours and asking simple questions about who passes by and why tells an operator more about the right format than any brochure describing the formats in the abstract. That homework costs nothing and can save a meaningful share of the budget from being spent on the wrong shape of business.
A flat ₱150,000 fee sits inside this budget no matter which end of it gets used, whether the total spend lands closer to ₱300,000 or closer to the full ₱600,000. That leaves a meaningful amount, sometimes as much as ₱450,000, for the physical build-out, equipment, signage, and the working capital a fuller operation needs before it settles into a routine. Payback holds steady at around eighteen months across the whole range. That suggests the extra spending at the higher end buys more capacity rather than a faster return. A leaner ₱300,000 build and a fuller ₱600,000 build are both expected to take about the same time to pay for themselves, just at different scales of daily transaction volume. That makes the choice less about speed and more about how big an operation the reader actually wants to be running eighteen months from now. Spending closer to the full amount only makes sense if the site can actually generate enough volume to use that extra capacity, otherwise the same eighteen months is spent carrying costs a leaner build would not have. Working capital deserves the same care as the fit-out spending, since a fuller build with weaker cash reserves can end up more fragile in its first months than a leaner one with money held back in reserve.
This budget suits someone ready to manage a real operation rather than run a counter alone. A build at this scale usually needs more than one person working it through the day. It fits someone with the patience for an eighteen-month payback window and the working capital to comfortably wait that long without the business needing to turn a profit early. It also suits someone who has already scouted a site that can support either a fuller kiosk or a proper inline store. The flat fee at this budget makes the site, not the fee, the deciding factor in which format to build. It is worth asking, before committing, how the training and support scale with the format chosen. Running a fuller inline operation with staff is a meaningfully different job from running a well-equipped counter alone, and the two call for different habits from the person managing them day to day. Someone who prefers working alone, without staff to schedule and train, may find the leaner end of this budget a better fit than the fuller build. This is not a budget for testing the idea on a whim. It rewards someone who has already decided this is the category and the scale they want, and is ready to give the site and the staffing the attention a build of this size needs from the very first week.
Now that you've seen what's here, a real advisor can help you shortlist and weigh the options against your budget. Free, at your pace.
Financing Readiness · Site Selection
Franchise Agreements · Multi-Unit Expansion
Low-Capital Startups
Low-Capital Startups · Site Selection
Are you a franchise advisor?Get your own workspace here
Compare payment & remittance franchises with other financial services businesses up to ₱600k, each with its own brands, fees and investment ranges.
Get honest answers on fees, payback and the best setups for your area, free and with no pressure.
Size alone should not impress you, even when two payment & remittance franchises are listed between ₱500k and ₱600k at ₱600k. A big pool can hold many near identical packages, which makes the choice feel harder than it is. Group lookalikes together and keep one from each group. That step can shrink the pool quickly, leaving you with a few really different packages to compare in detail. Differences are where your decision lies.
Comparable payment & remittance franchises at ₱600k cover kiosks with 2 franchises and inline stores with 2. Talking to people who work these setups reveals their daily demands better than any brochure. Ask a few current crew members what a normal shift involves, how many people share it and how long they stand, serve or prepare, then compare their answers with the staff and hours you can supply to see which format suits you.
To sum it up, ₱600k in a payment & remittance franchise usually buys a starting package that may include the franchise fee, equipment, initial stock, training, signage and opening support, depending on the franchisor. The package gets you started, while rent, permits and working capital usually stay with you. Gather written inclusion lists from every franchisor you are considering and compare them item by item before deciding.
Security for your outlet is a cost many owners forget when they plan around ₱600k. CCTV cameras, sturdy locks, roll-up shutters or an alarm may be needed, and some malls or landlords require them. Check what security the space already has, then decide what you must add to protect the equipment and stock you are investing in. Protecting the investment upfront is far cheaper than replacing everything after a break-in.
Talking with your spouse or household before raising ₱600k for a payment & remittance franchise matters as much as the money itself. Saving, borrowing or pledging assets affects everyone at home, and support is easier to keep when people agree early. Sit down together, share the full cost and how you plan to fund it, and settle what the family will do if the business needs more time to earn.
Provided you can handle a steady routine, a payment & remittance franchise at ₱600k can suit a beginner, since much of the work repeats day after day. Repetition helps you improve quickly, yet it can also grow dull. Ask a current owner what an ordinary week looks like and which tasks they enjoy least. If you can accept those tasks cheerfully, the routine is likely to suit you for the long run.
Yes, if ₱600k still leaves room for insurance, a cost many new owners skip. The two payment & remittance franchises quoting an investment between ₱500k and ₱600k may require coverage for fire, theft or liability under the contract, and some landlords insist on it too. Ask the franchisor and the property owner what policies they require, then get quotes from different insurers so the premium is part of your plan from the beginning rather than a late addition.
Compare how many payment & remittance franchises start at each budget level, from the smallest packages up.
Payment & Remittance franchises priced close to your budget, worth a look if you can stretch your savings or want to spend less.
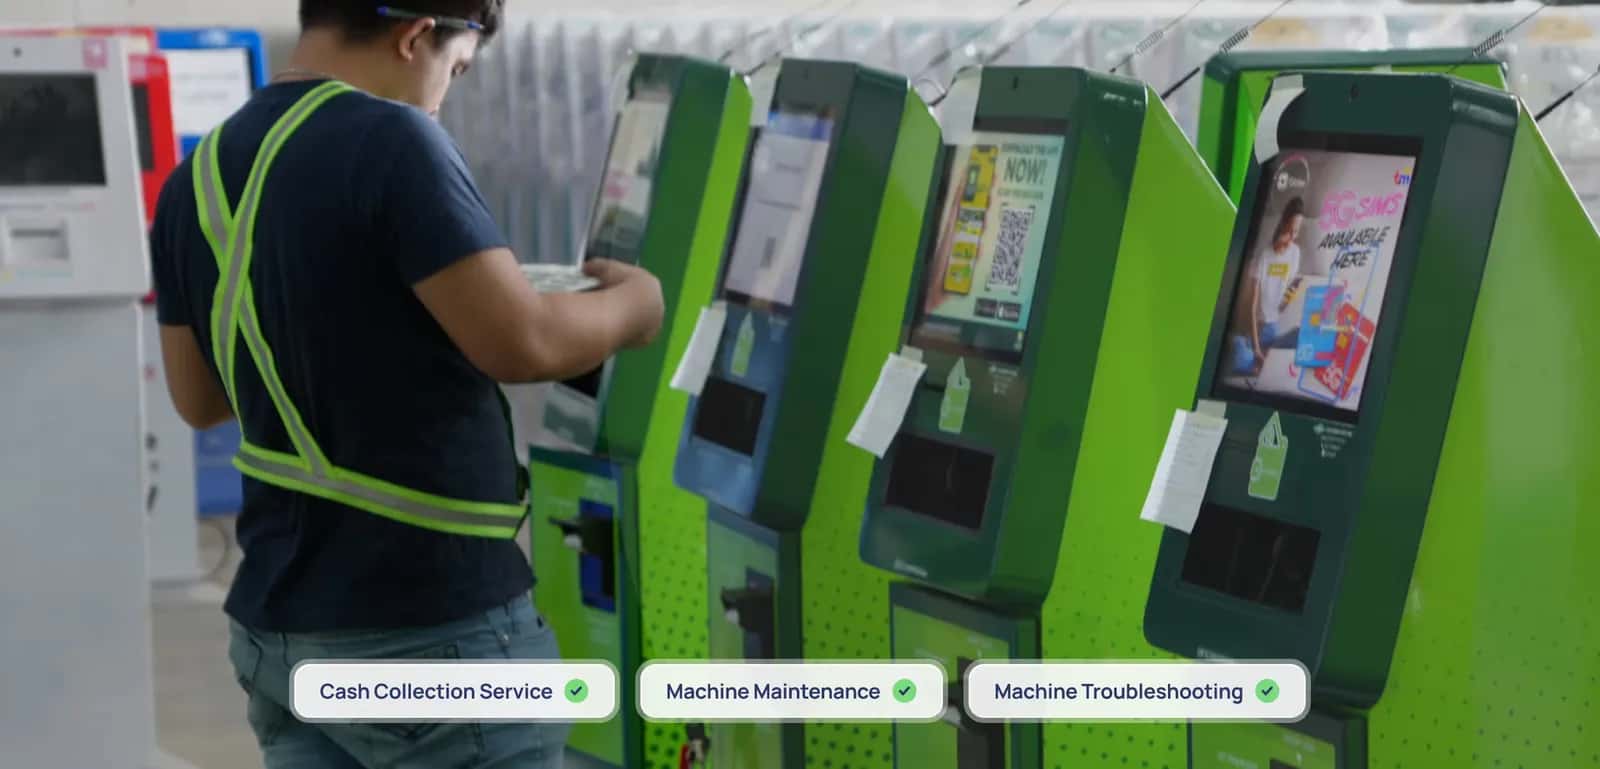
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center

Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Compare payment & remittance franchises with other industries at the same budget, each with its own brands, fees and investment ranges.
Carts, kiosks, and full restaurants.
72 brandsFrom ₱198k
Boy Kanin, Bente Silog, Buko Juan +69 more
See brands
Coffee, milk tea, and cold drink shops.
19 brandsFrom ₱250k
Cha Thai, CLT Cafe, Island Tea Co. +16 more
See brands
Bread, cakes, and pastry shops.
7 brandsFrom ₱350k
Empanada Nation, Remilly's Yema Cake, Big Smile Bread Station +4 more
See brands
Mini marts and convenience stores.
4 brandsFrom ₱350k
P. TOGO, Goldmine Farm to Market, Scents and Blends +1 more
See brands
2 brandsFrom ₱250k
Ink All You Can, Premium Graphics Asia Center (TRANSFER-IT)
See brands
Padala, parcel, and delivery outlets.
2 brandsFrom ₱300k
OKS Xpress Courier, SUREX
See brands
Drugstores and health supplement outlets.
2 brandsFrom ₱350k
ValueMed Generics Pharmacy, Well-Family Midwife Clinics
See brandsCompare industries by budget, daily work and payback before you choose one, free and with no pressure.
Learn practical inventory control steps for your Philippine franchise to cut waste, prevent loss, and protect your capital.
Aug 14, 2026 6 min read
Learn how non-compete clauses work when exiting a franchise agreement in the Philippines, protecting your investment after closing.
Jul 20, 2026 5 min read
Learn how to secure financing for your Philippine franchise, from preparation to approval. A practical guide for new operators and OFWs.
Jul 20, 2026 5 min read