CB Estrada Pawnshop
Financial Services
- Franchise fee
- ₱350k
- Total investment
- ₱2.5M–₱4.5M
🎁 Start Your 1 Month Free Trial of the Full Plan, Exclusively for Brands & Advisors.Get Started
Browse 15 financial services franchises in Negros Occidental, including 7 affordable franchise brands under ₱100k that pay back in 3 to 12 months, 6 medium-investment franchise brands between ₱100k and ₱1M that pay back in 9 to 21 months, and 2 premium franchise brands above ₱1M that pay back in about 24 months.
Updated
Financial Services
Payment & Remittance Center
Visit a branch
Payment & Remittance Center
Visit a branch
Payment & Remittance Center
Payment & Remittance Center
Payment & Remittance Center
Visit a branch

Payment & Remittance Center
Payment & Remittance Center
Negros Occidental has about 644 banks, pawnshops, lending and remittance offices among the 19,053 businesses on the map across its cities and towns, from shops and services to clinics and schools. Check what already operates near the spot you have in mind for your franchise.
Population
3,223,9552020 census
Per 10,000 residents
59businesses we track
Business locations are based on Overture Maps open data (October 21, 2026 release) and do not represent a complete census of all businesses.
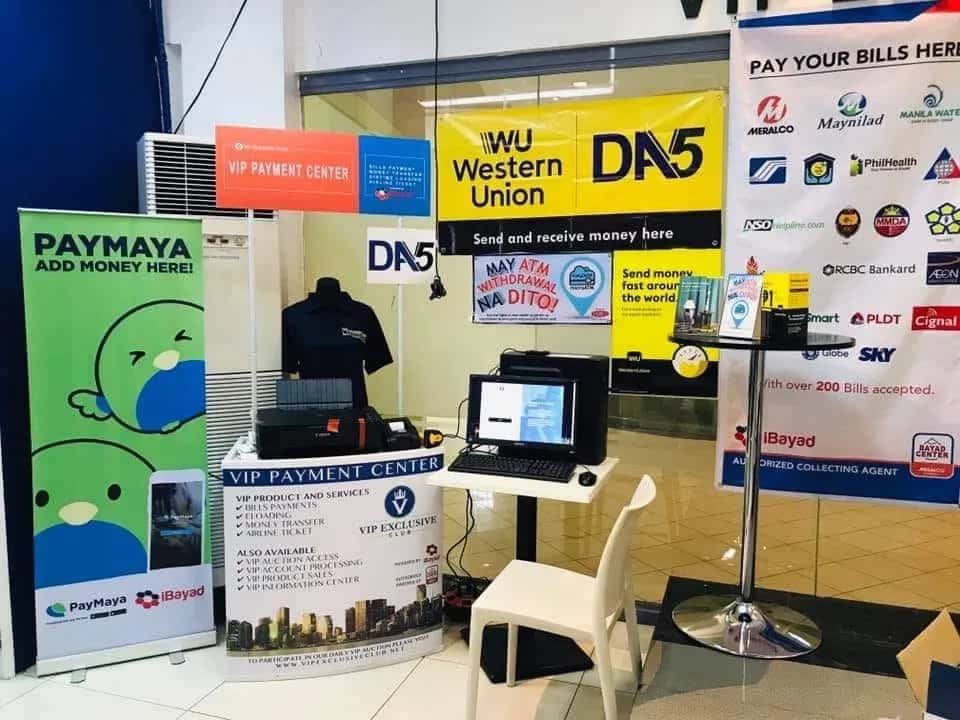
Financial services in Negros Occidental is offered locally as an inline store, a full counter inside a row of shops, and it asks between ₱2.5M and ₱4.5M to open. The province is a sugar-growing island economy with a busy capital city and mill towns along the coast, so bill payments, loan payments and money transfers move through it steadily. Smaller formats are open through the nationwide list for owners who want to begin with far less cash, which leaves an owner two very different routes to choose between.
The local inline store starts at ₱2.5M and goes up to ₱4.5M. The gap between the two comes down to the size of the counter, the number of tellers, the fit-out and the cash held for daily payouts. A larger store also needs a proper safe, a security guard and a visible location on a main street, all of which add to the budget. Nationwide, financial services brands begin around ₱19,500 for a very light setup and reach ₱4M, so a smaller starting point is open to someone who prefers to build gradually. What separates the cheapest and costliest setups is mostly the volume each is designed to handle. A small counter serves a neighbourhood, while a full store is meant to be the place a whole district goes for its transactions. Renting a good corner near a market, a terminal or a cluster of offices usually costs more, and that cost tends to pay back through steadier foot traffic.
Only a minority of financial services brands nationwide are set up to run from home or online, which makes the kiosk and the store the formats most owners will actually meet. The local offer in Negros Occidental is the store alone, so anyone who wants a kiosk beside a market entrance or a lighter home-based desk works from the nationwide side. Each format changes the daily work. A kiosk needs one or two people and a short opening checklist, while a store needs a team, a rota and a manager who can step in when a teller is absent. Sugar towns and city barangays also differ in how customers behave, since payday in a mill area brings a rush on a single afternoon, and a store copes with that rush better than a kiosk. A store also lets the owner add services over time as customers ask for them.
The local store carries a signing fee of ₱350,000, and its payback is quoted at two years. That is a long horizon compared with the lightest setups, but it matches an investment that runs into millions and depends on building a customer base that returns every week. Nationwide fees range from nothing to ₱400,000, so the local fee sits near the top of what any brand asks and should be weighed against the support that comes with it. An owner should ask for the training schedule, the software and the help offered when transaction volume is low in the first months. Timing matters in a sugar province, where household spending swells when the milling season pays out and thins afterwards, so a cash reserve for the quieter stretch keeps the store steady. Ask the brand for examples of how quickly a new store reached its usual volume, and plan the cash to last beyond that point.
A financial services store opens early, because workers pay bills and send money before their shift, and it usually closes only after the last remittance is settled. The day begins with counting the cash float and testing the systems, then moves through a steady flow of bill payments, transfers and cash-outs, each of which must be recorded and reconciled before closing. Staff turnover matters, since customers return to tellers they know, so training and fair pay repay themselves. Owners also spend time on compliance paperwork, on cash pickups and on the relationship with the brand's support team. Weather in the province affects the day too, as heavy rain can slow foot traffic and delay deliveries of cash, so a store that keeps a comfortable reserve on hand rarely has to turn anyone away. A dependable backup generator and a second internet line are cheap protection against the days when a storm knocks out power.
Now that you've seen what's here, a real advisor can help you shortlist and weigh the options against your budget. Free, at your pace.
Financing Readiness · Site Selection
Franchise Agreements · Multi-Unit Expansion
Low-Capital Startups · Site Selection
Low-Capital Startups
Are you a franchise advisor?Get your own workspace here
Choose a kind of financial services business and see only its brands in Negros Occidental, with their fees and investment ranges.
Get honest answers on fees, payback and the best setups for your area, free and with no pressure.
Negros Occidental has 15 financial services franchises open to new franchisees right now. Among them, one target Negros Occidental or one of its cities by name, so they likely know the local market already, and 14 take applications from anywhere in the country. For a nationwide franchisor, ask early how it supports a branch in Negros Occidental, from supply deliveries to staff training. By starting investment, the mix is seven affordable, six medium-investment and two premium franchises. Narrow the list to three or four options and ask each for its latest franchise package.
Neighbors who have tried to open a shop can tell you more than any list, and in Negros Occidental that list shows San Carlos with the most financial services franchises at 15, then Bacolod with 14 and Bago with 14. Ask people in your preferred city who rent out space or run small stores how long it took them to find a spot and what surprised them. Fold those lessons into your search plan before you contact a single franchisor.
Prices begin at ₱20k for financial services franchises in Negros Occidental, and the next option up is ₱50k. If your savings fall between the two, ask the cheaper franchisor what an upgrade would add and what it would cost. You might get much of what you want without the higher price. If your savings cover both, compare their inclusions line by line and price what each leaves out.
Hiring reliable people affects whether a financial services franchise in Negros Occidental stays on track for the 4 to 22 months franchisors quote. Finding staff can be easy in some areas and slow in others, and an understaffed shop loses sales. Ask current owners how long it took to fill their positions and what wage it took, and check local job posts to see what others offer.
You will find one financial services franchise here with a small network of five cities or fewer. These smaller franchisors tend to know the local market well. Check that their supply chain can keep up as they grow.
Know your crowd before you choose, as seven financial services franchises in Negros Occidental start below this budget. Students, office workers, commuters and families buy in very different ways and at different hours. Match what you offer and your opening schedule to the people who actually pass your spot. A package that suits a school entrance may do poorly beside a quiet subdivision gate.
Some landlords in Negros Occidental will trade a higher monthly rate for lighter upfront payments, and you can use that. If your capital is tight, ask whether the advance or deposit can be reduced in exchange. For a financial services franchise, work out which mix of rate and upfront cash you can carry, since a small deposit with a rate your sales cannot cover is no bargain.
Access by commuters often matters more than frontage alone. Many customers in Negros Occidental reach shops by jeepney, tricycle or on foot, so a spot near a stop or a busy corner can outperform a prettier one. Map the transport routes around the address you are considering for your financial services franchise, and show that map to the franchisor as part of your proposal.
Supply flexibility often grows with trust. Many franchisors loosen early rules for branches that have paid on time and ordered consistently for a while. Ask what privileges owners earn over time, such as smaller minimums, credit terms or priority delivery, and what record you must build to qualify. This tells you whether the early supply burden is temporary or a permanent part of the system.
Compare how many financial services brands take franchisees in each city of Negros Occidental.
Every industry in Negros Occidental, by how much it takes to start and by the kind of space it runs from.
By budget
Franchises from other industries that also take franchisees in Negros Occidental and cost about the same to start.
Waffle Shop
Visit a branch
Street Food & Snacks
Shawarma
Visit a branch
Ice Cream & Desserts
Milk Tea & Boba
Visit a branch
Ice Cream & Desserts
Visit a branch
Packaged Snacks
Visit a branch
Fries & Potato Snacks
Compare financial services franchises in Negros Occidental with other industries there, each with its own brands, fees and investment ranges.
Carts, kiosks, and full restaurants.
248 brandsFrom ₱3k
Kwatogs, Konam, Minute Burger +245 more
See brands
Coffee, milk tea, and cold drink shops.
55 brandsFrom ₱17k
Zagu, Macao Imperial Tea, Barista Choi +52 more
See brands
Mini marts and convenience stores.
49 brandsFrom ₱500
Folded & Hung, Halo Mobile Clothing, Monterey Meatshop +46 more
See brands
Bread, cakes, and pastry shops.
33 brandsFrom ₱17k
Waffle Time, Mister Donut, Goldilocks +30 more
See brands
Salons, barbershops, and spa services.
32 brandsFrom ₱200k
Big Apple Express Spa, Bruno's Barbers, Body and Sole Spa +29 more
See brands
Drugstores and health supplement outlets.
17 brandsFrom ₱300k
Farmacia ni Dok, Gamot Publiko, Generika Drugstore +14 more
See brands
15 brandsFrom ₱250k
ALOHA (Abacus Learning of Higher Arithmetic), Kumon, STI +12 more
See brands
Gyms, studios, and sports facilities.
9 brandsFrom ₱1.6M
GoFit Gym, Snap Fitness 24/7, Gold's Gym Philippines +6 more
See brands
Purified and mineral water stations.
9 brandsFrom ₱100k
Aquabest, Aqualipure, Crystal Clear +6 more
See brands
Self-service and full-service laundry shops.
7 brandsFrom ₱400k
CS Laundry, Tipidsulit Laundromat, Quicklean One Hour Laundry +4 more
See brands
Padala, parcel, and delivery outlets.
7 brandsFrom ₱10k
Alin Cargo Express, Ninja Van, J&T Express +4 more
See brands
7 brandsFrom ₱25k
SMB Travel & Tours, South Shore Travel Biz, RedDoorz +4 more
See brandsCompare industries by budget, daily work and payback before you choose one, free and with no pressure.
Understand how franchise contracts work in the Philippines. Learn about term lengths and renewal rights to secure your business for the long term.
Jul 20, 2026 5 min read
Learn how to secure financing for your Philippine franchise, from preparation to approval. A practical guide for new operators and OFWs.
Jul 20, 2026 5 min read
Discover why low franchise fees in the Philippines can lead to higher costs, and how to evaluate true investment value for your new business.
Jul 20, 2026 5 min read